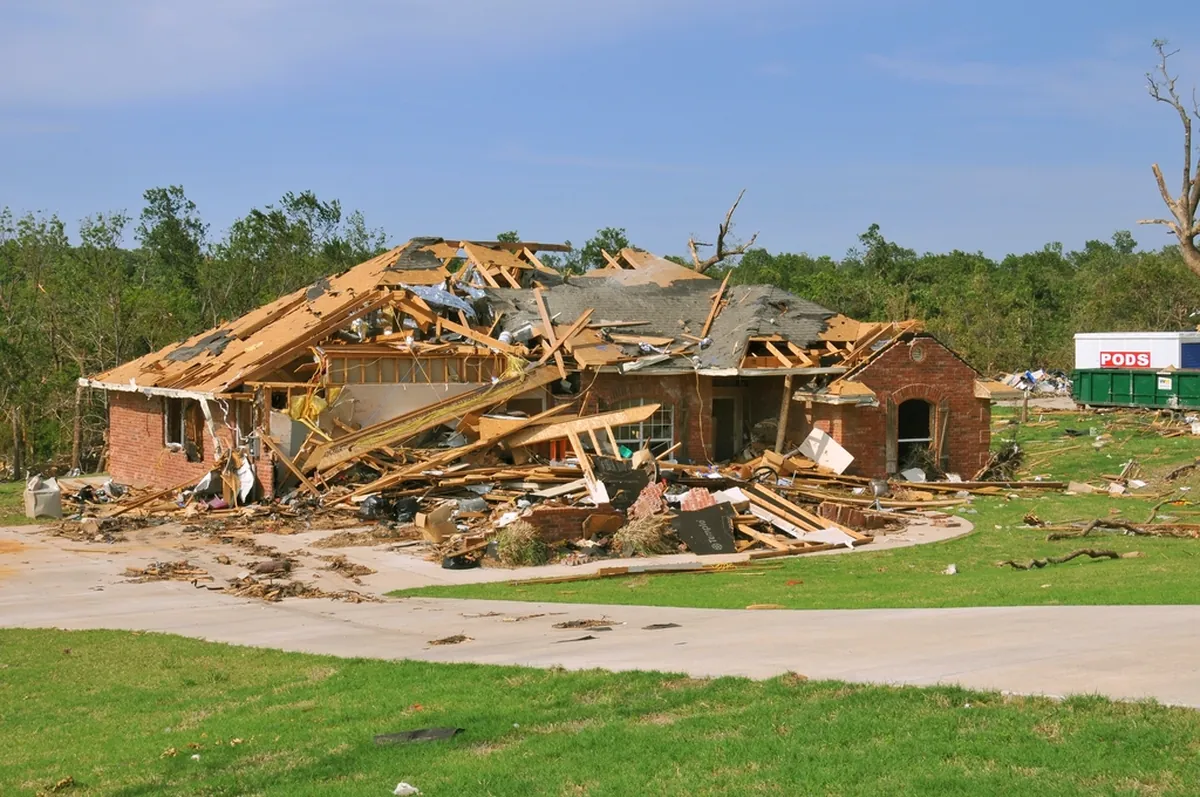
Michigan’s wind history is longer than most people think
Michigan isn’t hurricane country, but it has a serious record of damaging wind. The June 8, 1953 Flint–Beecher tornado remains one of the deadliest in U.S. history. The Palm Sunday outbreak of April 11, 1965 tore across southern Michigan, and a tornado struck downtown Kalamazoo on May 13, 1980. More recently, tornadoes hit Dexter in March 2012, Gaylord in May 2022 and Portage in May 2024, while the August 24, 2023 storms produced several tornadoes in southeast Michigan, including Livonia. Straight-line winds count too: the Labor Day 1998 derecho damaged homes and trees across southern Michigan.
What wind does to a building
Wind damage ranges from a few lifted shingles to a home pushed off its foundation. In between are the losses most likely to end up in appraisal:
- creased or unsealed shingles that look flat from the ground but have lost their bond;
- siding panels torn loose or cracked, often on the windward side;
- soffit, fascia and gutter damage;
- broken windows and the water intrusion that follows;
- structural racking, damaged trusses or shifted walls after a tornado;
- detached garages, sheds, fences and pole barns.
Creased shingles and the wear-and-tear argument
One of the most frequent wind disputes is whether creased or unsealed shingles were caused by a storm or by age. Shingles that lose their seal over time can still be lifted and creased by a specific wind event. Careful documentation of crease patterns, direction and location helps separate storm damage from deterioration.
Tornado losses: scope gets complicated fast
After a tornado, the question is often not repair versus replace but how much of the structure can be saved. Engineering opinions may differ. Debris removal, demolition, temporary housing and ordinance or law upgrades can become large items, and many policies cap some of these. When a home is a total loss, the dispute may turn on rebuilding cost at current Michigan prices rather than what the house cost to build originally.
To see what a percentage deductible means in dollars, use the percentage deductible calculator.
How we build a wind appraisal
We begin with the storm itself: the date, the reported wind direction and the timing of your notice. Then we inspect every elevation and roof slope, documenting damage in a way that ties it to the event. Our estimate accounts for Michigan labor pricing after a widespread storm, when contractor demand can push costs up. We meet with the insurer’s appraiser to reconcile differences, and anything unresolved goes before the umpire. An award signed by two of the three sets the amount of loss.
We work statewide, from Kalamazoo and Portage to Gaylord and the Thumb. If you’re weighing whether to invoke appraisal or wait for a reinspection, the should you demand appraisal? guide covers the factors. Remember that appraisal decides amount, not coverage, and that deadlines generally run from the date of loss. A Michigan attorney can advise on timing. We are independent appraisers, not public adjusters, and we don’t give legal advice.
Frequently asked questions
How do you tell wind damage from old shingles?
We look at crease patterns, the direction and location of damage, sealant condition and how damage lines up with the storm’s wind direction. Clear photos and measurements carry the most weight.
Is a tornado total loss handled differently in appraisal?
The process is the same, but the focus shifts to the full cost to rebuild, including demolition, debris removal and code upgrades within your policy’s limits.
Does my policy have a separate wind deductible?
Some Michigan policies do, often stated as a percentage of the dwelling limit. Check your declarations page or ask your agent.